Smaller Brazilian Wheat Harvest Opens New Opportunities for Argentine Exports

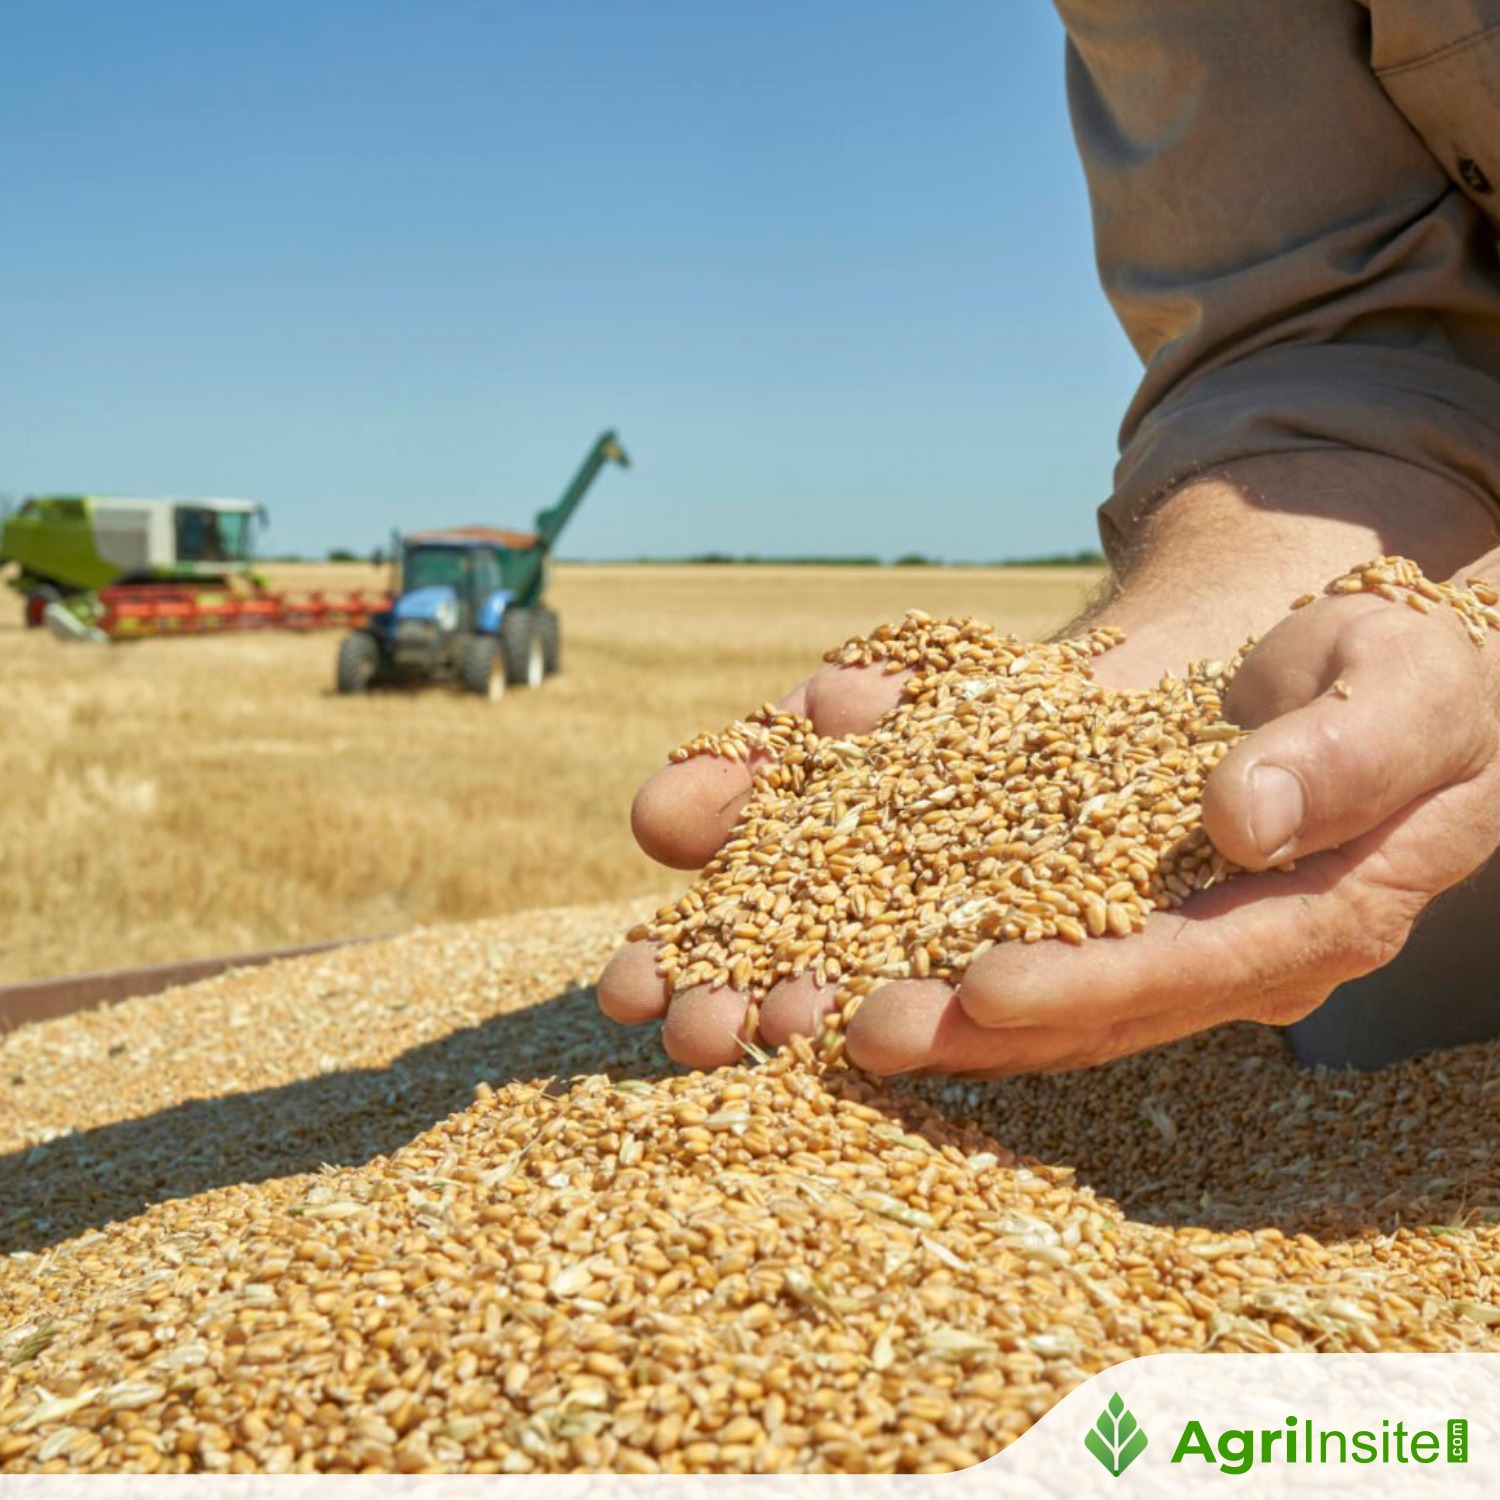
Argentina shipped a record nearly 2 million tonnes of wheat during September-October, while Brazil’s declining harvest and quality issues could push imports to unprecedented levels. With approximately 29 million tonnes available, Argentina could benefit from stronger Brazilian demand, although renewed Black Sea competition remains a risk.
Argentine wheat exports are ending the marketing year with an unusually strong performance, while attention is shifting toward a market that could undergo significant changes in the coming months. Brazil, a traditional buyer of Argentine wheat, is facing a smaller harvest and will need to source unprecedented volumes of grain from abroad. For Argentina, which has ample supplies available, this presents an opportunity.
The outlook was examined by the Rosario Board of Trade (BCR) in a report reviewing the 2025/26 marketing year. Between September and October, Argentina is estimated to have shipped nearly 2 million metric tons (Mt) of wheat worldwide, an all-time record for the two-month period, according to preliminary data from maritime agency Nabsa S.A. The exchange’s analysts described the performance of Argentine wheat exports as “among the most exceptional on record.”
Containerized wheat shipments by sea also increased. According to Datamar data, Argentina exported 651 TEUs of wheat between January and September. Shipments rose particularly sharply between August and September 2026, increasing 150%.
The increase is also evident in domestic logistics activity. In October, more than 980,000 metric tons of wheat were delivered by truck to Argentine ports, the highest volume recorded for that month in recent years. Greater Rosario accounted for a record 76% of wheat arrivals at the country’s ports.
However, the international market, which has so far worked in Argentina’s favor, is beginning to show some less favorable signs. According to the latest report from SovEcon, Russia is estimated to have exported approximately 2.9 Mt of wheat in October, its highest monthly volume since the beginning of the new marketing year, as shipments were redirected through Baltic ports. Russia and Ukraine were also expected to resume peace negotiations in Abu Dhabi in the coming weeks, raising the possibility of a de-escalation of the conflict and a normalization of shipments from the region. If that happens, Argentina could begin to lose some of the ground it has gained as one of the leading suppliers of wheat.
Brazil’s Wheat Harvest Affected by Rainfall
Against this backdrop, attention is turning to Brazil. Rainfall during the winter harvest affected wheat quality, particularly in São Paulo and Paraná, where production suffered and grain quality fell below industry standards. Brazil’s National Supply Company (Conab) projects production of 5.73 Mt for the 2026/27 marketing year, down 27.2% from the previous year.
Lower production will also reduce Brazil’s wheat self-sufficiency. According to U.S. Department of Agriculture (USDA) data on domestic consumption and production, Brazil is expected to cover just 47% of its needs with domestically grown wheat, compared with 63% in the previous marketing year. This would be the lowest level since 2019/20.
The shortfall will have to be covered by imports. In its latest supply and demand report, the USDA projects Brazilian wheat imports of 7.5 Mt, exceeding the previous record in its historical series. Some private estimates, including those from the Brazilian Wheat Industry Association and Safras & Mercado, place the figure between 8.5 Mt and 9 Mt.
Ample Supplies Could Support Argentine Wheat Exports
Argentina is expected to enter this period with wheat supplies available. According to the BCR, carryover stocks from the current marketing year into the next would exceed 5 Mt, while production is currently estimated at 23.8 Mt. Together, these figures would bring total available supplies to approximately 29 Mt.
At the upper end of private forecasts, Brazil’s projected imports of 8.5 million to 9 million metric tons would represent approximately 29% to 31% of Argentina’s estimated wheat availability. Brazil sources wheat from several countries, so these figures should not be interpreted as demand that Argentina alone would supply. They nevertheless indicate the scale of the potential market.
Brazil’s proximity also offers Argentine wheat suppliers logistical and commercial advantages. Established trade relationships with Brazilian flour mills could become particularly relevant as those buyers seek grain to compensate for a smaller domestic harvest affected by quality problems.
The BCR nevertheless cautions that favorable conditions are not assured. Argentina’s position will depend partly on how international wheat markets develop as the next marketing year approaches. Brazilian demand could help support Argentine shipments if Russian and Ukrainian exports begin to return to normal, bringing renewed competition.
For Argentine exporters, the challenge will be to secure part of that demand before global supply conditions change.
Soybeans and Corn: Strong Shipments, Falling Prices
The broader grain market continues to show sustained export activity, although prices are declining. In soybeans, shipments from the soybean complex totaled 30.2 Mt in soybean-equivalent terms between April and October, according to Argentina’s National Institute of Statistics and Censuses (INDEC) and preliminary October figures from Nabsa. This represents 66% of projected exports for the entire marketing year, including soybeans and their byproducts, broadly in line with the average for previous years.
The domestic market, however, has not kept pace with this activity. As of the week ending October 28, total commitments for the 2025/26 marketing year had reached 31.36 Mt, according to Argentina’s Secretariat of Agriculture, Livestock and Fisheries (SAGyP). This leaves 29.3% of production unsold, 16.8 percentage points above the historical average. Meanwhile, domestic processors continue to purchase imported soybeans. Paraguay harvested a record crop exceeding 12 Mt for the first time, according to the USDA. Argentina’s soybean imports have reached 5.5 Mt so far this marketing year, the second-highest level this century, surpassed only by 2022/23, when a severe drought reduced domestic production to 20 Mt.
As for prices, soybeans in Rosario traded at around 540,000 Argentine pesos, or $350 per metric ton, this week, their lowest level since late August. Prices have followed the downward trend in Chicago, where the November soybean contract fell to a low of $436 per metric ton. Futures have now recorded four consecutive weeks of losses, reaching an 11-week low.
Corn shipments, meanwhile, were exceptionally strong in October. According to Nabsa, Argentina is estimated to have exported more than 3.9 Mt during the month, with Vietnam standing out as a major destination after purchasing approximately 1 Mt.
Despite this pace, the domestic market continues to carry a large volume of unsold grain. The BCR estimates that approximately 8.8 Mt of corn purchased by exporters has yet to be shipped, the highest absolute volume in the historical series and equivalent to 26% of total purchases. More than 14.4 Mt also remains unsold in the domestic market, another record. Against this backdrop, corn prices in Chicago have fallen nearly 20% from their late-September highs, trading at $173.50 per metric ton in the middle of the week.
To Read more about Wheat News continue reading Agriinsite.com
Source : DatamarNews