Indian Wheat Demand Holds Firm as Global Export Prices Soften

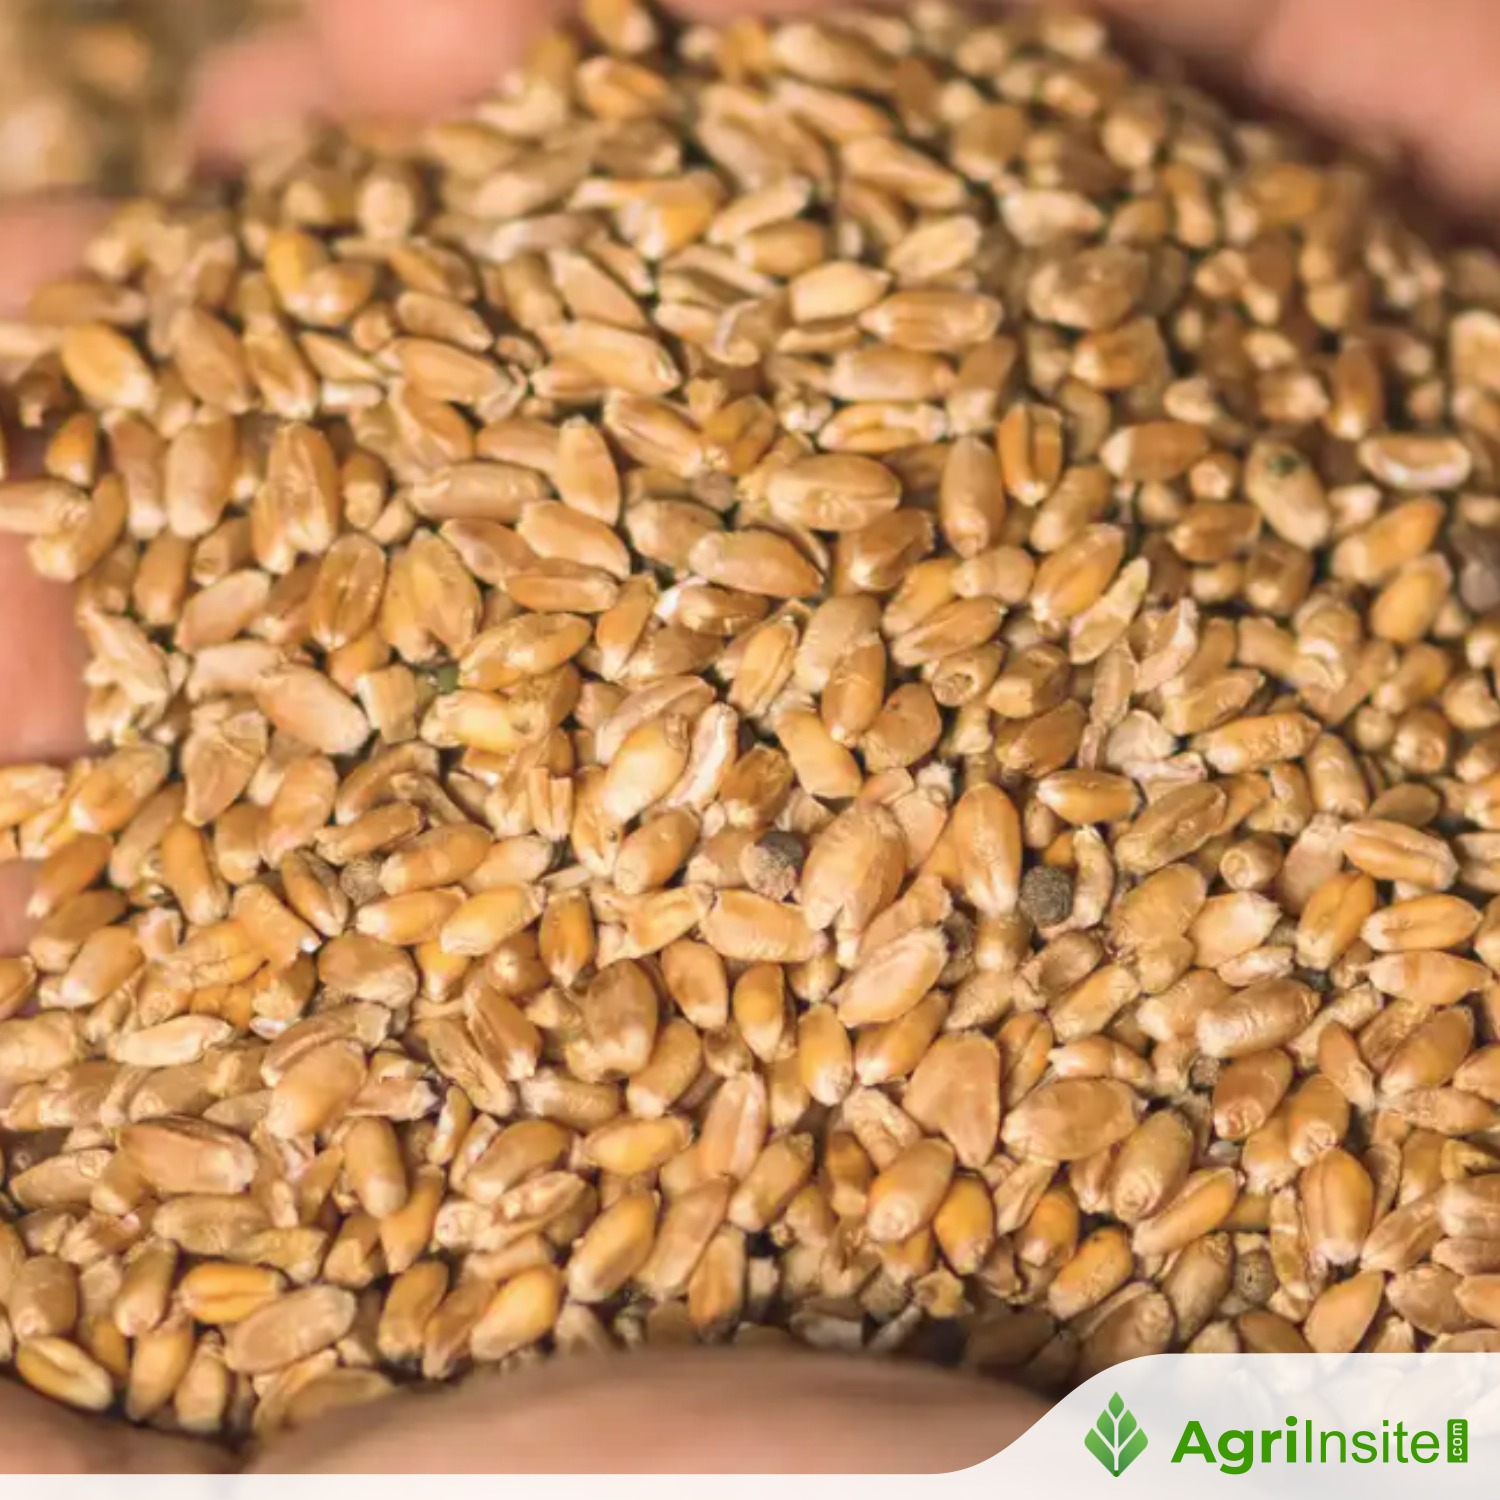
Indian wheat prices remain stable to mildly firm as strong flour-milling demand and controlled government stock releases support domestic markets. In contrast, global export quotations have weakened around 5% month-on-month amid subdued buying, ample supplies and intensifying competition among major exporters.
Indian wheat demand from flour mills remains firm, but international export quotations remain weak, widening the gap between domestic and global markets. Government stock releases, transportation costs and quality differentials are shaping this divergence, while some grain segments show limited trading as participants await clearer supply signals. Across the broader wheat complex, export quotations in key origins have eased in recent weeks amid subdued buying interest and comfortable stocks. In India, however, stable processing demand and calibrated government stock auctions are preventing a parallel decline in domestic prices. This split is prompting mills and traders to reassess sourcing strategies and hedge exposure, particularly as winter wheat sowing advances and weather risks for the upcoming crop slowly come into focus.
Prices
International wheat export quotations remain under pressure, with benchmark wheat indices lower in recent weeks on softer export demand and competition among major origins. Recent data show global wheat export prices declining around 5% month-on-month, led by weaker North American quotations and ongoing discounts in the Black Sea region as exporters vie for limited demand.
Against this backdrop, physical wheat indications in the Black Sea and Europe have also softened, reflecting cautious buying and shipping disruptions that limit upside despite constrained logistics. By contrast, India’s domestic market has not mirrored these declines, as firm flour-milling demand and managed government stock sales under schemes such as OMSS continue to underpin internal price levels ahead of peak festival consumption.
In the cash market, our most recent EUR quotations show modest weakness in Ukrainian and German wheat over the last two weeks, in line with the broader international trend. In Odesa (Ukraine, CPT), food wheat grade 2 is currently indicated at 0.169 EUR/kg and grade 3 at 0.156 EUR/kg, both slightly below mid-October highs. Feed wheat in Odesa (CPT, 14% moisture max) is at 0.142 EUR/kg, down from earlier peaks. German feed wheat in Drentwede (EXW, 14% moisture max) is quoted at 0.232 EUR/kg, also easing from 0.25 EUR/kg seen in mid-October.
| Origin | Location | Specification | Delivery | Latest price (EUR/kg) | Trend vs mid-Oct |
|---|---|---|---|---|---|
| Ukraine | Odesa | Wheat grade 2 | CPT | 0.169 | Softer |
| Ukraine | Odesa | Wheat grade 3 | CPT | 0.156 | Softer |
| Ukraine | Odesa | Feed wheat, 14% moisture | CPT | 0.142 | Softer |
| Germany | Drentwede | Feed wheat, 14% moisture | EXW | 0.232 | Softer |
Supply & Demand
The core tension in today’s wheat market lies between relatively weak international demand and still-solid domestic consumption in India. Flour mills there are described as maintaining firm offtake, especially ahead of festival-related demand, even as global trade flows slow and some importers delay purchases in expectation of further price declines. This divergence is amplified by India’s high internal cost structure, including transport and procurement costs, which keeps local values above export parity and limits interest in international offers.
Globally, ample closing stocks after a strong 2025/26 harvest and only modest growth in consumption are weighing on export quotations. Market reports highlight subdued import buying and increased competition among exporters, particularly in the Black Sea and EU, where sellers are discounting to clear commitments. In India, however, sizeable government-held inventories and ongoing stock releases through e-auctions are being carefully paced to prevent domestic prices from spiking while ensuring steady pipeline flows to processors.
Quality differentiation is another important driver. A portion of the government’s wheat stocks consists of relaxed-quality grain, which limits its direct substitutability for higher-grade millers’ wheat and supports premiums for suitable grades. At the same time, procurement policies and stock regulations shape the relative profitability of holding wheat versus selling it forward, contributing to the “wait-and-see” stance in some grain market segments as traders assess the scale and pricing of further government stock releases.
Fundamentals & India Focus
In India, grain market commentary underscores that flour-milling demand for wheat remains relatively firm, particularly from biscuit and processed-food manufacturers that require reliable pipeline coverage. Government interventions via stock releases are central to balancing this demand against large public inventories, which have accumulated after improved procurement campaigns and earlier concerns about inflation. The result is a domestic market that appears structurally well supplied but not oversupplied at the level of millers’ preferred grades.
Internationally, wheat fundamentals lean bearish to neutral. Recent global assessments indicate that after a record or near-record crop in the previous marketing year, world ending stocks remain comfortable, particularly in key holders such as India. Export competition has intensified, and several origins are facing slower-than-expected shipment programs, reinforcing the downward pressure on FOB values. Despite this, internal logistics costs and risk premia in some exporters, especially in and around the Black Sea, prevent the full transmission of cheaper inland values to seaborne offers.
For India, these cross-currents create a consistent pattern: domestic wheat prices decouple from global weakness due to regulatory frameworks, transport costs from surplus to deficit regions, and grade availability. Traders with access to suitable milling quality report limited arbitrage opportunities between domestic and imported wheat, reinforcing a primarily inward-looking price formation where government auction terms and local demand are more important than changes in Chicago or Paris futures.
Weather Outlook for Key Wheat Regions
Weather is becoming a relevant factor mainly for newly sown or establishing winter wheat. In the U.S. Central and Southern Plains, forecasts point to generally above-normal temperatures with scattered showers over the coming 7–10 days, which is broadly supportive for emergence but may leave some areas drier than ideal. In the Northern Plains, additional precipitation is expected, with some potential for mixed rain and early-season wintry weather.
In the Black Sea region, outlooks indicate near- to above-normal temperatures with only limited rainfall across parts of western Russia, while Ukraine should see more frequent, though still scattered, showers. This pattern implies that soil moisture recovery remains an issue in some Russian wheat belts even as conditions in Ukraine are closer to adequate. For India, attention will increasingly turn to moisture availability and temperature during the early rabi sowing window following recent heavy rainfall episodes in parts of the country, but no immediate large-scale threat to wheat planting has emerged so far.
Trading Outlook
- Indian buyers: With processing demand firm and government auctions actively clearing stocks, domestic users should prioritize coverage of near-term requirements but can be selective on further forward purchases, especially if additional stock releases are announced.
- Exporters (Black Sea/EU): Weak global demand and intensifying competition suggest maintaining flexible pricing strategies and focusing on quality and logistics reliability, as outright price strength appears limited in the short term.
- Import-dependent consumers: Given soft international quotations and still-comfortable global stocks, gradual scale-down buying on further price weakness may be prudent, while watching winter weather risks and any escalation in regional shipping disruptions.
- Speculative participants: With fundamentals tilted slightly bearish but weather and geopolitical risks still in play, a cautious, range-trading bias with tight risk limits seems appropriate rather than aggressive directional positioning.
3-Day Price Indication
Over the next three trading days, international wheat prices are likely to remain slightly soft to sideways, reflecting ample exportable supplies and only moderate buying interest. Ukrainian CPT Odesa values for food and feed wheat, as well as German EXW feed wheat, are expected to trade within a narrow band around current levels, barring any abrupt weather or geopolitical shocks.
In India, domestic wheat prices are anticipated to stay broadly stable to mildly firm in the very short term, underpinned by steady demand from flour mills and ongoing, but controlled, government stock releases. Market activity in some other grain categories may remain subdued as traders continue to wait for clearer information on future supply availability and policy signals.
To Read more about Wheat News continue reading Agriinsite.com
Source: CMB News