Large stocks and weak exports may push Russian wheat prices even lower

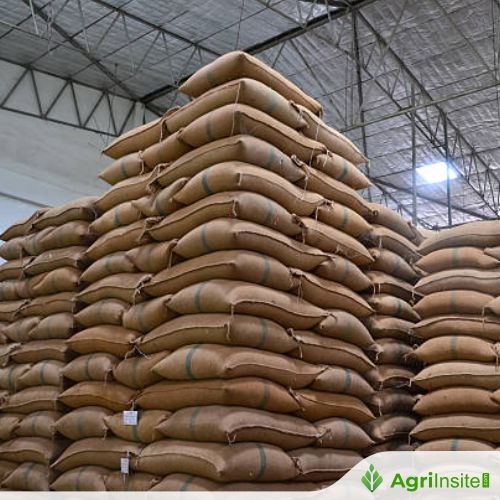
Russia’s grain stocks could reach 28–34 million tonnes in MY 2026/27 if Azov-Black Sea export disruptions persist, with wheat carryover potentially reaching 22 million tonnes. Lower exports, weak domestic demand and limited milling capacity could push Class 3 wheat prices below RUB 10/kg.
Problems with grain exports through the Azov-Black Sea basin could lead to a sharp accumulation of stocks in Russia and further declines in domestic wheat prices. According to Vladimir Petrichenko, head of ProZerno, grain carryover stocks in MY 2026/27 could reach 28–34 mln tons depending on developments in maritime logistics.
Deep-water southern ports previously accounted for around 57% of Russia’s grain exports, while another 27% was shipped through river ports and offshore transshipment. Grain exports in July–September may total around 8.5 mln tons compared with 14 mln tons a year earlier, while alternative routes are unlikely to fully compensate for lost Black Sea capacity.
According to ProZerno estimates, without a full recovery of Black Sea exports, Russia may ship only around 39 mln tons of grain this season. Under an optimistic scenario, if Black Sea shipments begin to recover from early 2027, exports could rise to 45 mln tons, still below the potential 59 mln tons. This would leave 14–20 mln tons of grain unexported.
The strongest pressure is expected in the wheat market. Even under a favorable scenario, wheat exports are estimated at 33 mln tons compared with a potential 45–46 mln tons, while carryover stocks could reach 22 mln tons. According to the analyst, the domestic market will be unable to absorb such volumes due to weaker demand from the livestock sector and limited milling capacity.
The accumulation of grain stocks is already putting additional pressure on prices. Petrichenko believes that the current level of around RUB 10/kg for Class 3 wheat including VAT, or about $118/t, is not yet the bottom and prices could fall further. A similar situation is seen in the flour market, where prices also continue to decline.
Russia is trying to partly offset lower Black Sea exports through the Baltic, Far East, overland routes and the Caspian Sea. However, even higher shipments to Iran, which could become one of the key buyers of Russian grain this season, will not be enough to fully absorb the surplus. Large stocks and weak exports may therefore continue to pressure the domestic grain market throughout the season.
To Read more about Wheat News continue reading Agriinsite.com
Source : UkrAgroConsult